

A gas station canopy is usually covered under the station’s commercial property policy, but only as well as it is scheduled. Insurers generally want the canopy listed with its own replacement value, and the wind deductible, collapse wording, and canopy signs all need a check. Nationwide, a small station’s full program typically runs $4,000 to $10,000 or more a year, and a larger station’s can run over $15,000.
Why Is the Canopy Its Own Line on the Schedule?
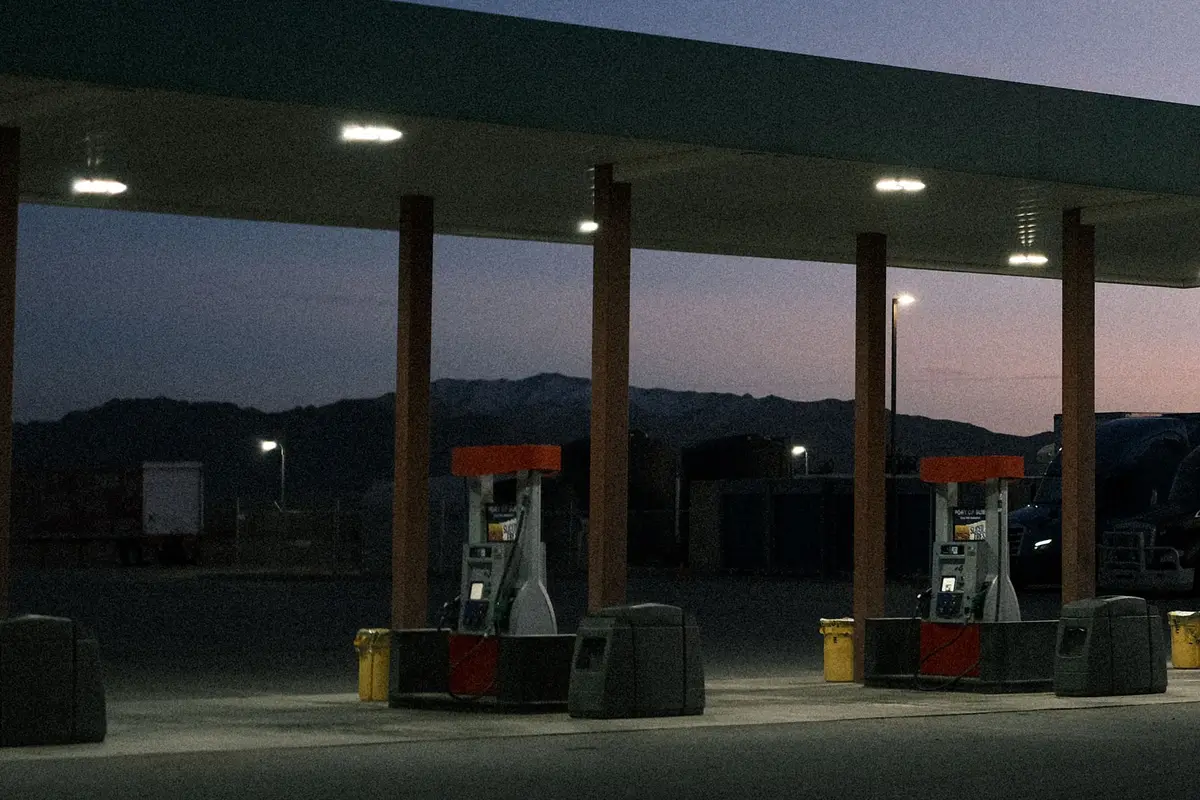
A canopy is a large, exposed, steel structure that stands apart from the store. If the property schedule lists only the building, the canopy may be undervalued or missed. Underwriters on petroleum property usually ask for the canopy, dispensers, signs, and building as separate values so each is insured at the cost to replace it.
What Damages Canopies Most Often?
Wind and hail. These are usually covered perils, but exposed regions often carry a separate wind or hail deductible, sometimes written as a percentage of value. Coastal stations should also read Florida gas station hurricane insurance for the wind and flood split.
Snow and ice. Collapse from the weight of snow or ice is commonly addressed in property forms, subject to their terms. Wear, rust, and deterioration are usually excluded, so maintenance records help.
Vehicles. Tall trucks and box vans strike canopy edges and columns. The National Association of Insurance Commissioners explains that auto property damage liability pays for damage an at-fault driver causes to someone else’s property. Our guide on who pays when a car hits a gas pump walks through the same steps.
Illustrative scenario. A box truck clips the edge of a station’s canopy and keeps going. The fascia and two light fixtures are torn down. The station’s property policy pays after its deductible because the canopy was scheduled with its own replacement value. A nearby station that had listed only its building found its canopy underinsured after a similar loss. The scenario is hypothetical and is not a coverage determination.
What About Signs, Lights, and Lost Sales?
Canopy signs, brand fascia, and lighting may be listed with the canopy or as separate items. Some policies limit outdoor signs unless they are scheduled, so check. If the forecourt has to close while the canopy is repaired, business income coverage can pay lost income, subject to its waiting period and terms.
What Else Should an Owner Check?
- the canopy’s replacement value and when it was last updated;
- the wind or hail deductible in dollars, not only as a percentage;
- collapse wording and any exclusions for deterioration;
- how signs and lighting are scheduled;
- clearance markings and bollards that reduce vehicle strikes.
Branded stations should also check what the fuel brand’s image program requires for canopy repairs, covered in branded vs. unbranded gas station costs.
How Do I Check My Canopy Coverage?
Send the station’s property schedule through the quote form or call 317-942-0549. We check the canopy value, deductibles, and sign coverage.
The bottom line
A gas station canopy is usually covered under the station’s commercial property policy, but only as well as it is scheduled. Underwriters want the canopy listed with its own replacement value, and the owner should check the wind or hail deductible, how collapse from snow or ice is handled, and whether canopy signs and lights are included. When a vehicle hits a canopy column, the driver’s auto liability usually pays first. Nationwide, a small station’s full program typically runs $4,000 to $10,000 or more a year, and a larger one can run over $15,000.
Frequently asked questions
Is a gas station canopy covered by insurance?
Usually, under the commercial property policy, if it is scheduled correctly. Many insurers want the canopy listed separately with its own replacement value. An undervalued or missing canopy is one of the most common gaps on a station’s property schedule.
Does insurance cover a canopy damaged by wind or hail?
Wind and hail are typically covered perils on commercial property, often subject to a separate wind or hail deductible in exposed areas. Check that deductible, because it can be much larger than the standard one.
What if a canopy collapses under snow or ice?
Collapse from the weight of snow or ice is commonly addressed in commercial property forms, subject to their terms. Read the collapse wording on your policy, and keep maintenance records, since wear and deterioration are usually excluded.
Who pays when a truck hits a canopy?
Usually the at-fault driver’s auto insurance, under property damage liability. If the driver cannot be found or is uninsured, the station’s property policy pays after its deductible, and the insurer may pursue the driver.
How much does gas station insurance cost with a canopy?
Nationwide, a small station’s program covering general liability, property, liquor liability, and storage tank typically runs $4,000 to $10,000 or more a year, and a larger station’s can run over $15,000. The canopy’s value and exposure affect the property portion.